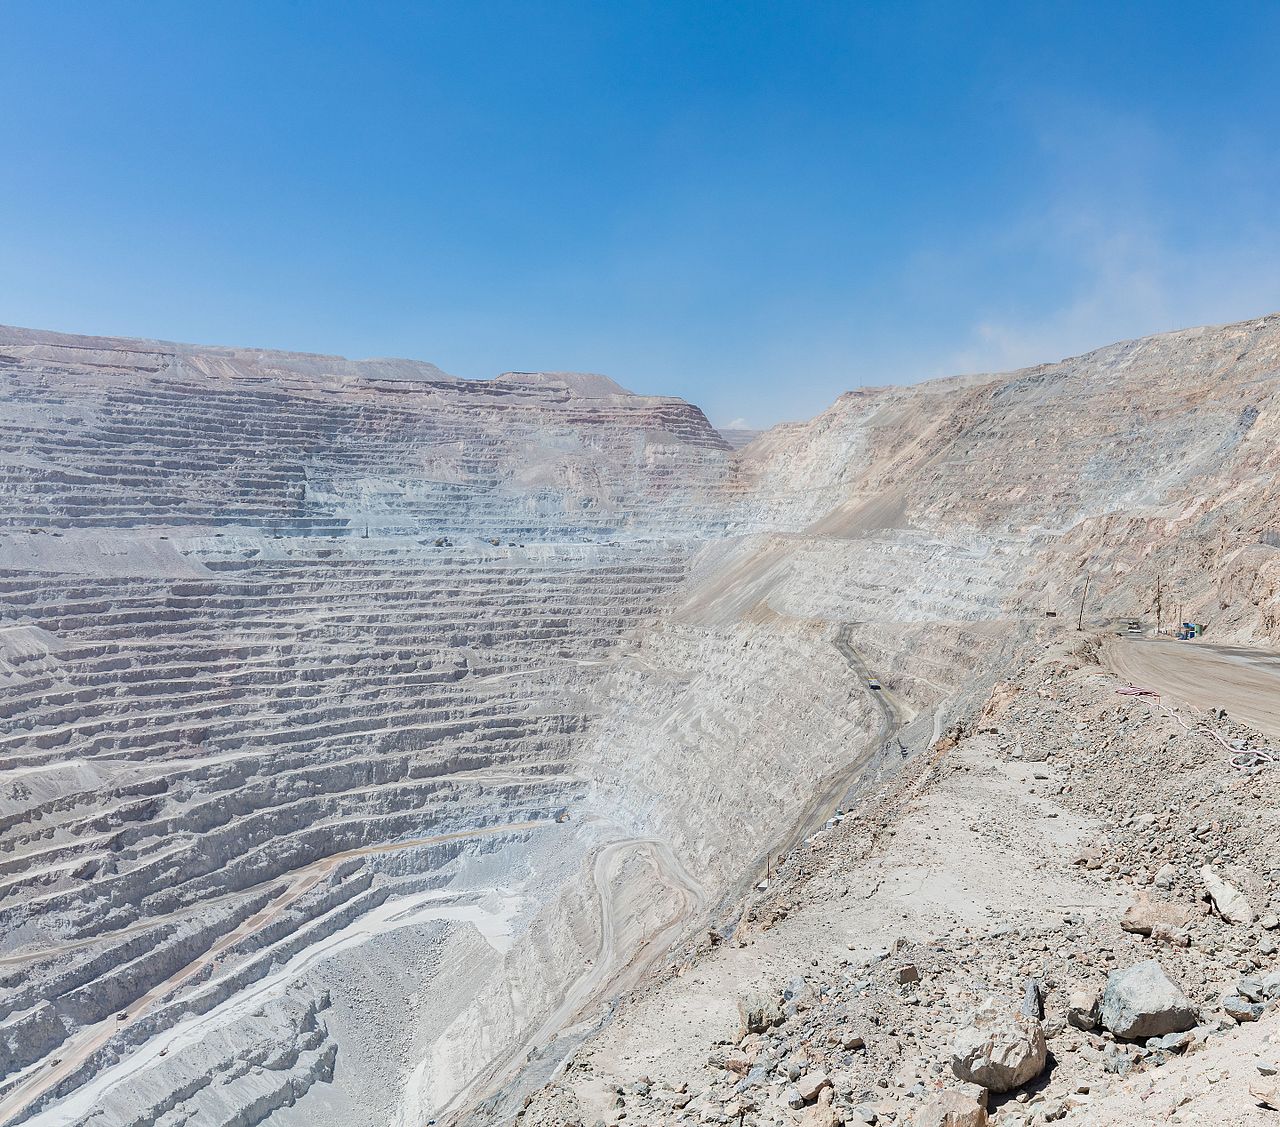
Reopen to Close: Panama Turns a Copper Restart Into a Shutdown Plan
A three-minister commission told President Mulino on 30 September to negotiate a Cobre Panama restart that pays for the mine's own permanent closure, with a fixed end date and no expansion. First Quantum fell as much as 36 percent.

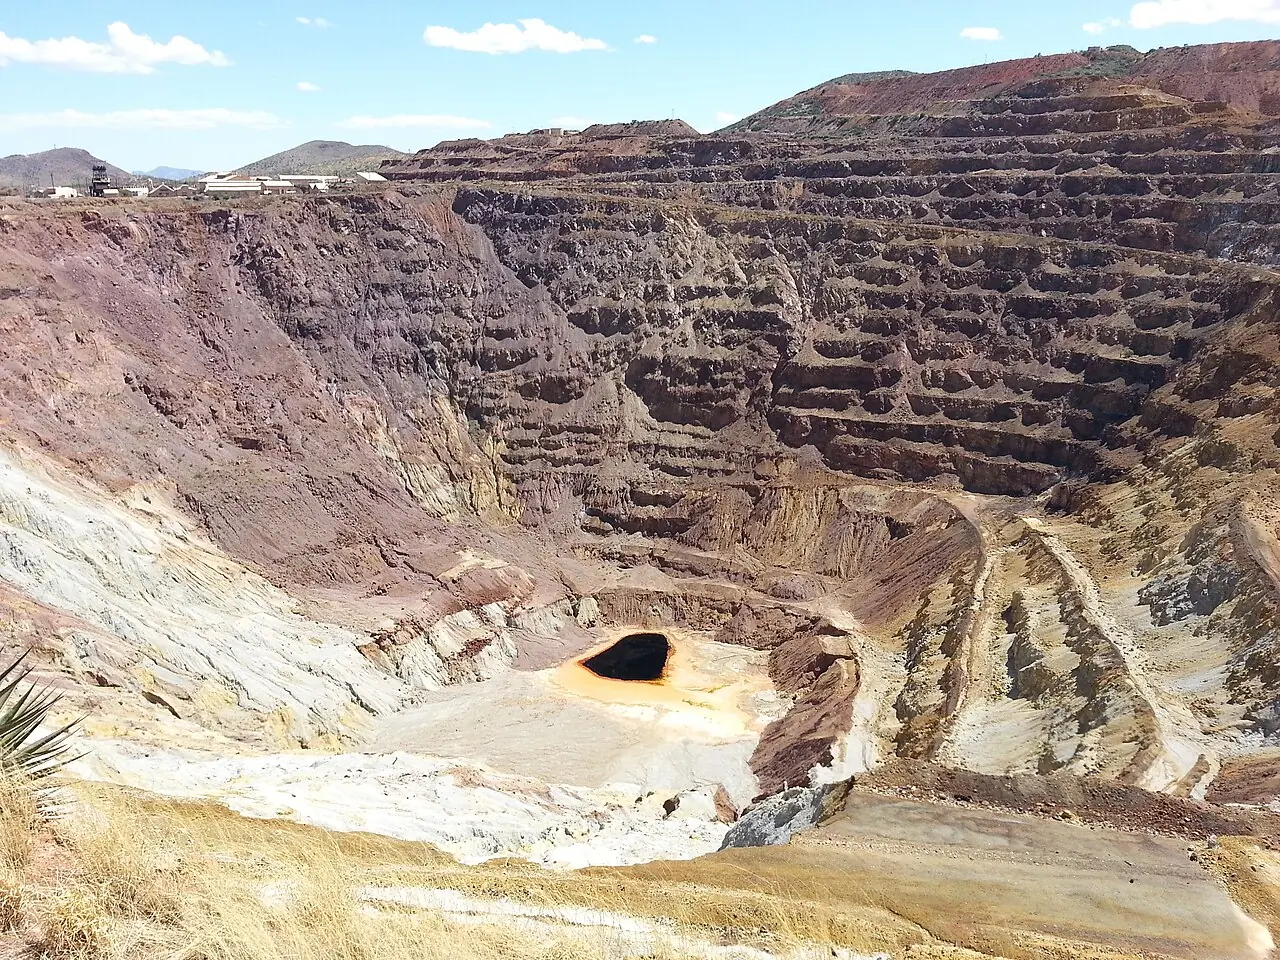
The copper market has spent two years treating Cobre Panama as a supply option that would eventually come back. On 30 September a Panamanian government commission told President José Raúl Mulino to convert that option into an exit. The three-minister body recommended exploring a new arrangement with First Quantum Minerals (TSX: FM) that would let the mine resume operations while setting out a path toward its eventual closure, a framing MINING.COM described as reversing expectations that officials were moving toward reviving one of the world’s largest copper operations [MINING.COM, 30 September 2026].
This is not a restart with conditions attached. It is a closure with a revenue phase in front of it, and the difference matters for anyone modelling copper into the AI buildout.
What’s happening
- The commission recommended Mulino order the final but orderly closure of Cobre Panama, after reviewing an audit by independent Swiss consultants alongside economic, environmental and legal assessments. It stressed this is not a final decision, which rests with the president [MINING.COM, 30 September 2026].
- The mine produced about 1.5 percent of global copper before mining stopped in 2023, and accounted for roughly 5 percent of Panama’s GDP that year according to First Quantum [MINING.COM, 30 September 2026].
- Eight principles were laid out for any new arrangement. The binding ones: a definitive closure date with no renewal or extension, a prohibition on further expansion of the mine site, operations adapted to a progressive shutdown, and a site rehabilitation mechanism. Any deal should also resolve outstanding international arbitration [MINING.COM, 30 September 2026].
- First Quantum shares plunged as much as 36 percent in early Toronto trading, last changing hands at C$31.1 for a market value of C$25.9 billion, about $18.2 billion [MINING.COM, 30 September 2026].
- Commerce and Industries Minister Julio Moltó, at a press conference: “A closure isn’t done in one year, nor in five years.” Economy and Finance Minister Felipe Chapman backed an orderly closure while arguing Panama should not bear its cost, and Environment Minister Juan Carlos Navarro said the mine should never have been built [MINING.COM, 30 September 2026]. First Quantum declined to comment.
The door June opened, the lock September fitted
This desk covered the June audit as a door opening: Panama’s environment ministry published the SGS environmental audit on 19 June and an inter-agency task force began evaluating the mine’s legal, economic, technical and environmental future, which put suspended tonnes back on the table [Tantalum Strategy Desk archive, 21 June 2026]. The September report is that same process arriving at the opposite destination. The state is not deciding whether Cobre Panama produces again. It is deciding on what terms it stops.
The eight principles are the substance. A definitive closure date with no renewal converts a world-class orebody into a depleting annuity. A prohibition on expansion caps the asset at its current footprint regardless of price. Cobre Panama was First Quantum’s largest revenue generator before the shutdown, about 40 percent of company revenue [MINING.COM, 30 September 2026], which is what the 36 percent share move was pricing.
The physical market is not waiting. On the same day, Chile’s statistics agency INE reported August copper output down 12.8 percent year on year, 369,500 tonnes against 423,643 tonnes in August 2025, hit by July storm effects and lower ore grades at major sites [Reuters via MINING.COM, 30 September 2026]. That is 54,143 tonnes lost in a single month, desk arithmetic from the INE figures. First Quantum still forecasts 30,000 to 40,000 tonnes of copper from previously mined stockpiles at Cobre Panama for all of 2026 [MINING.COM, 30 September 2026]. Chile lost more copper in August than Panama will contribute all year.
Brazil angle
Brazil is running the opposite playbook and getting paid for it. Vale Base Metals confirmed on 13 August it is proceeding with the Coarse Particle Flotation project at the Salobo Copper Complex, the largest copper operation in Brazil, adding 6 million tonnes of annual processing capacity to reach 42 million tonnes per year and up to approximately 30,000 tonnes per year of incremental copper in concentrate. Start-up was accelerated to the first half of 2028, about a year early, with the IBAMA construction license received ahead of schedule. Capex was cut to approximately $215 million from $225 million to $275 million, with Wheaton Precious Metals providing $40 million, leaving VBM at roughly $175 million and an IRR above 50 percent [Vale Base Metals release via PR Newswire, 13 August 2026].
VBM CEO Shaun Usmar put the contrast plainly in that release: “At a time when our industry is struggling to bring new copper supply online, VBM is bucking trends with the early delivery of its copper growth projects.” The company says its strategy is expected to lift copper production to approximately 700,000 tonnes per year by 2035, supported largely by its Brazilian resource base and Carajás pipeline against more than 53 million tonnes of contained copper in reserves and resources including inferred [Vale Base Metals release via PR Newswire, 13 August 2026].
Panama has jurisdictional risk that closes mines. Brazil has a permitting authority issuing construction licenses ahead of schedule. That gap is the whole Brazilian copper thesis, and today it got a data point.
US angle
For US buyers the Panama recommendation lands on an already distorted market. In mid-August, Comex copper traded roughly $400 a tonne over the LME three-month price as metal moved to the United States ahead of possible tariffs on refined copper, with record CME stocks above 700,000 short tons, about 635,000 tonnes, and LME stockpiles falling for a 42nd straight day to 204,975 tonnes [MINING.COM, 14 August 2026]. Research house BMI then saw a full-year 2026 average approaching $13,500 a tonne, up from $12,700, and flagged a phased tariff scenario of 15 percent from 2027 and 30 percent from 2028 [BMI via MINING.COM, 14 August 2026].
The US exposure here is financial, not operational. First Quantum is TSX-listed and the mine is Panamanian, so no American permit sits in the decision loop. What Washington controls is the tariff schedule that determines whether the metal that does exist keeps flowing to US warehouses, and permanently removing a source that supplied about 1.5 percent of global copper makes that arbitrage more expensive to sustain, not less.
China angle
China’s position is the mirror image of the American one. Its smelters have been squeezed by concentrate scarcity for more than a year. In late November 2025 the China Smelters Purchase Team agreed to cut production by over 10 percent in 2026, and Chen Xuesen, vice president of China’s Nonferrous Metal Industry association, said the state-backed body “firmly opposes any free and negative processing” of copper concentrate while noting China had halted about 2 million tonnes of planned new smelting capacity [Reuters via MINING.COM, 28 November 2025]. Benchmark three-month copper was $11,009.50 a tonne on that date, a marker of how far the market has travelled since.
Concentrate, not furnace capacity, is the binding constraint, and the Democratic Republic of Congo’s ban on concentrate exports tightened it further [MINING.COM, 14 August 2026]. A permanent Cobre Panama closure removes concentrate, which is precisely the input China is short of. Expect Beijing’s response to run through equity and offtake in the African Copperbelt rather than through any statement about Panama.
What it means
The AI buildout’s copper problem gets framed as a demand story. It is increasingly a jurisdiction story. The market had been carrying Cobre Panama’s tonnes as recoverable. If Mulino follows the commission, that inventory of hope is written down, and the supply curve into the 2030s loses a source no greenfield project can replace on the same timeline. A government study published in September found the 2023 closure had already eliminated close to 36,000 jobs and cut taxes and royalties to the state by nearly $1.4 billion [MINING.COM, 30 September 2026]. That is the political arithmetic that makes a revenue-generating wind-down attractive to Panama and a poor substitute for supply to everyone else.
The desk’s own indexes are reading the stress. As of 26 September, TAI stood at 99.7, with materials sub-index TAI-M at 97 and down 3 percent year to date against power sub-index TAI-P at 107.9 and up 7.9 percent [Tantalum index data, as of 2026-09-26]. Power is repricing upward while the physical inputs lag. A permanent Panamanian closure is the kind of event that closes that gap from the materials side.
What to watch
- Mulino’s decision. The recommendation is explicitly not final. Watch whether a definitive closure date with no extension survives into whatever Panama actually puts to First Quantum.
- The arbitration. Any agreement is meant to resolve outstanding international proceedings. A settlement figure, or First Quantum choosing to press its claims instead, tells you whether a negotiated wind-down is real.
- Chile’s September INE print, due October. August was 369,500 tonnes and 12.8 percent down. A second consecutive double-digit decline would put the top producer and a large suspended mine on the subtraction side of supply in the same quarter.