Saudi Arabia announced a heavy rare earth resource with no grade. Washington had already agreed to fund the refinery.
Prince Abdulaziz bin Salman used the IAEA General Conference to disclose 110 million tonnes of ore at Jabal Sayid, with no grade and no contained metal. The US agreed to finance 49 percent of the Saudi separation plant last November, and dysprosium and terbium are still on China's control list.

Saudi Arabia picked a nuclear conference to make a rare earth announcement, and most of the wires read it backwards.
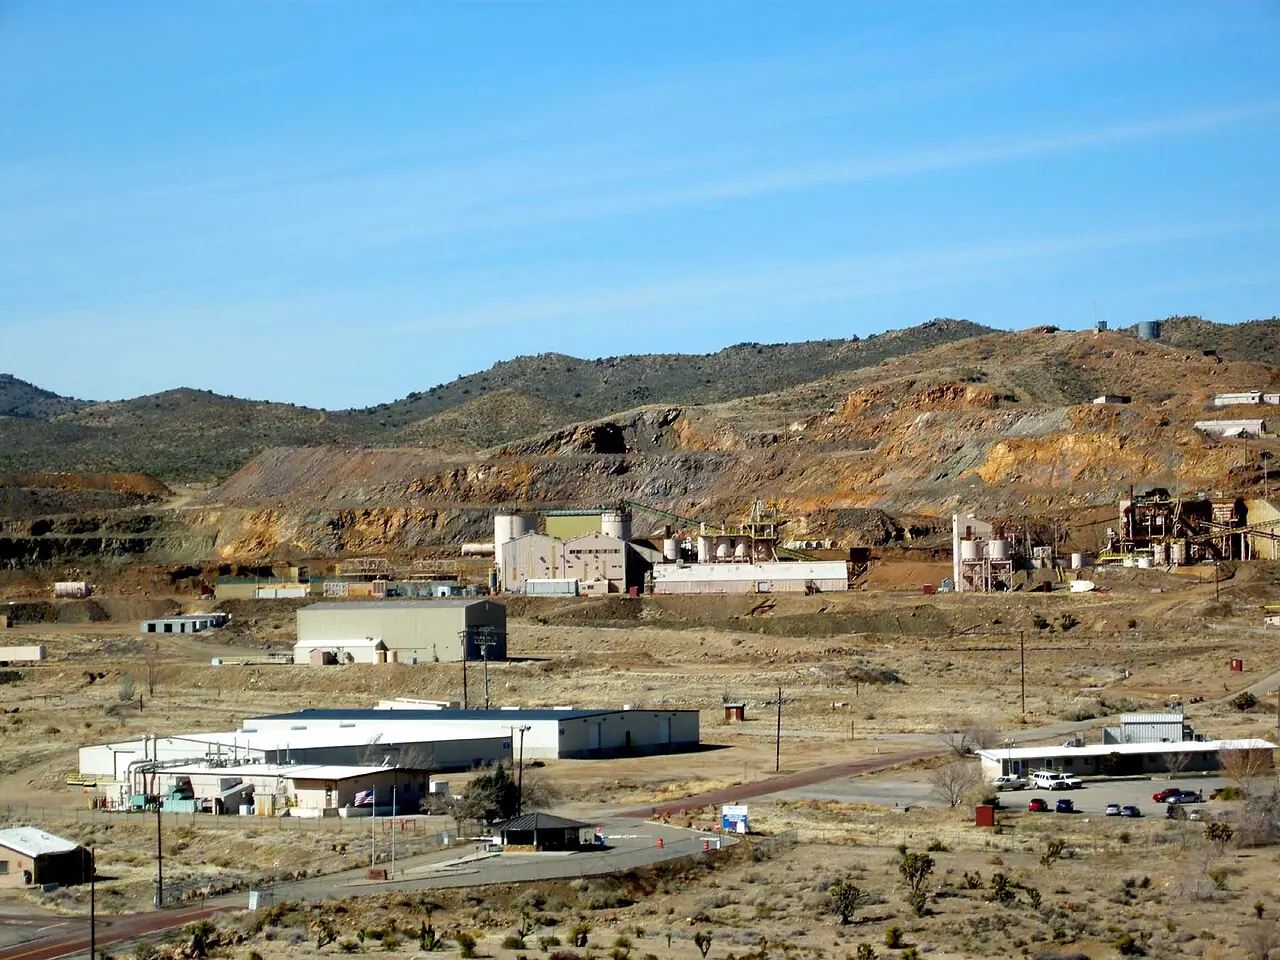
On Monday, at the 70th regular session of the International Atomic Energy Agency General Conference in Vienna, Energy Minister Prince Abdulaziz bin Salman disclosed an estimated 110 million tonnes of ore at the Jabal Sayid project in the Madinah region [Mining.com, 2026-09-14; Arab News, 2026-09-14]. The headlines that traveled furthest called it a uranium find. The minister’s own words did not.
What’s happening
- The verbatim claim: “Exploration and geological studies at the Jabal Sayid project in Madinah have revealed estimated resources of around 110 million tonnes of ore with high concentrations of rare earth minerals, especially the heavy elements, alongside promising concentrations of uranium” [Arab News, 2026-09-14]. Rare earths lead the sentence. Uranium is the third clause.
- No grade was disclosed and no contained uranium was estimated. Mining.com said so explicitly, noting that ore tonnage alone does not establish the size of a uranium resource [Mining.com, 2026-09-14].
- The minister called the project “among the most significant rare earth mineral resource sites currently under development globally” [The National, 2026-09-14].
- Jabal Sayid sits roughly 350 km northeast of Jeddah. A CSIS analysis, citing figures from the Saudi Ministry of Industry and Mineral Resources and state miner Ma’aden, ranks the site fourth globally, with about 552,000 tonnes of heavy rare earths including dysprosium and terbium, about 355,000 tonnes of light rare earths, and a co-located uranium resource near 31,000 tonnes [Arab News, 2026-09-14, citing CSIS].
- Neither source says the CSIS tonnages and Monday’s 110 million tonne figure describe the same envelope. If they did, the implied rare earth oxide grade would be roughly 0.8 percent and the implied uranium grade roughly 280 parts per million (desk arithmetic). Our read is that 280 ppm points to byproduct recovery, not a standalone uranium mine, consistent with the minister separately flagging recovery from fertilizer production [Mining.com, 2026-09-14].
One date note: Mining.com places the remarks on Monday, while The National wrote Tuesday in one paragraph and Monday in another. We treat Monday as the date.
The US angle
This is not a geology story. It is a financing story, and the financing predates the geology by ten months.
After Crown Prince Mohammed bin Salman’s November 2025 visit to Washington, the two countries signed a Strategic Framework for Cooperation on critical minerals, metals and uranium. Under it the US Department of Defense agreed to finance 49 percent of a new rare earth processing plant in the Kingdom, with Ma’aden holding a controlling 51 percent alongside MP Materials. Then on 22 July 2026, Energy Secretary Chris Wright and Prince Abdulaziz signed a Section 123 agreement alongside a bilateral safeguards deal, which the Department of Energy said provides the legal foundation for a decades-long, multibillion-dollar partnership. One provision is a study that could lead to US companies building a uranium enrichment plant on Saudi soil [Arab News, 2026-09-14; The National, 2026-09-14, citing the Wall Street Journal].
The sequence runs: Washington agrees to finance the separation plant, Washington signs the fuel cycle agreement, and only then does Riyadh announce what the plant might separate.
The China angle
The elements named at Jabal Sayid are precisely the ones Beijing has not released.
China’s November 2025 suspensions were real but partial. MOFCOM Announcement No. 70 shelved six October directives, and No. 72 suspended Article 2 of Announcement No. 46 until 27 November 2026. What was not suspended is Announcement 18 (2025), which added seven medium and heavy rare earths to the Dual-Use Items Control List: samarium, gadolinium, terbium, dysprosium, lutetium, scandium and yttrium, along with their oxides, alloys and magnet materials. Those licensing obligations remain in force [Clark Hill, 2025-11-24].
Terbium and dysprosium are the two heavy elements named in the CSIS figures. They are also the two that keep high-temperature magnets working in the generators, fans and grid equipment a data center campus runs on. A Saudi heavy rare earth resource matters to Washington for one reason above all: it sits outside a control list that has not been lifted.
The Brazil angle
Brazil spent the same fortnight doing the opposite thing.
On 2 September the Senate approved PL 2.780/2024, instituting the National Policy on Critical and Strategic Minerals, with R$5 billion in fiscal incentives, a guarantee fund, and a National Council holding veto power over changes of corporate control, transfers of Union assets and the granting of mineral titles. The text passed essentially unchanged and went to presidential sanction [ClimaInfo, 2026-09-02, citing Folha de S.Paulo].
The contrast is uncomfortable. Riyadh disclosed a resource with no grade and already has a 49 percent foreign-financed separation plant behind it. Brasília has published grades, an operating mine and a real heavy rare earth district, and has just built a council to gate foreign partnerships. In the same window, a US company with the US government among its shareholders completed the purchase of Serra Verde, the only rare earth miner operating in Brazil [ClimaInfo, 2026-09-09].
Brazil is legislating leverage. Saudi Arabia is banking it.
What it means
The Gulf demand case is not hypothetical. Saudi data center capacity grew sevenfold, from 68 MW in 2021 to 467 MW in the first quarter of 2026, and Humain, the PIF vehicle launched in May 2025, targets 1.9 GW of AI compute by 2030 and more than 6 GW by 2034 [Fortune, 2026-09-09]. A kingdom building gigawatts of compute needs firm power and it needs magnets, and it is now claiming the upstream of both. Whether it has either is a question about grade, and grade is the one number nobody published.
Our own indexes are consistent with a market that has not priced this. TAI stands at 103.2, down 4 percent on the week, with materials at 102.2 and power at 106.2. SOV50, which tracks the sovereignty trade directly, sits at 112.8 and fell 5.45 percent [Tantalum indexes, updated 2026-09-12]. Sovereignty announcements are running ahead of sovereignty cash flows.
What to watch
- A grade, or a resource statement to a recognised code. Until Ma’aden or the Saudi Geological Survey publishes a JORC or NI 43-101 style estimate, the 110 million tonne figure is a tonnage of rock, not a resource. The absence of a grade ten months after the refinery financing was agreed is itself the signal.
- Congressional review of the Section 123 agreement. The administration submitted the Saudi nuclear deal to Congress on 26 August 2026 [The National, 2026-08-26]. These agreements run a statutory review period, and the enrichment study is the contested provision.
- 27 November 2026, when Announcement 46’s Article 2 suspension lapses. Announcement 18’s controls on terbium and dysprosium never lapsed, so the question is whether Beijing reinstates the broader package. If it does, every ex-China heavy rare earth tonne reprices, including tonnes not yet drilled to a grade.


