Germany brings its rare earth fund to Brasilia: six projects, one magnet plant, and a bet on Brazil over China
Foreign Minister Wadephul joined MME, BNDES, and ApexBrasil for an embassy event that put MagBras and six exploration companies in front of German capital. The message: Berlin wants partnership, not just purchase.

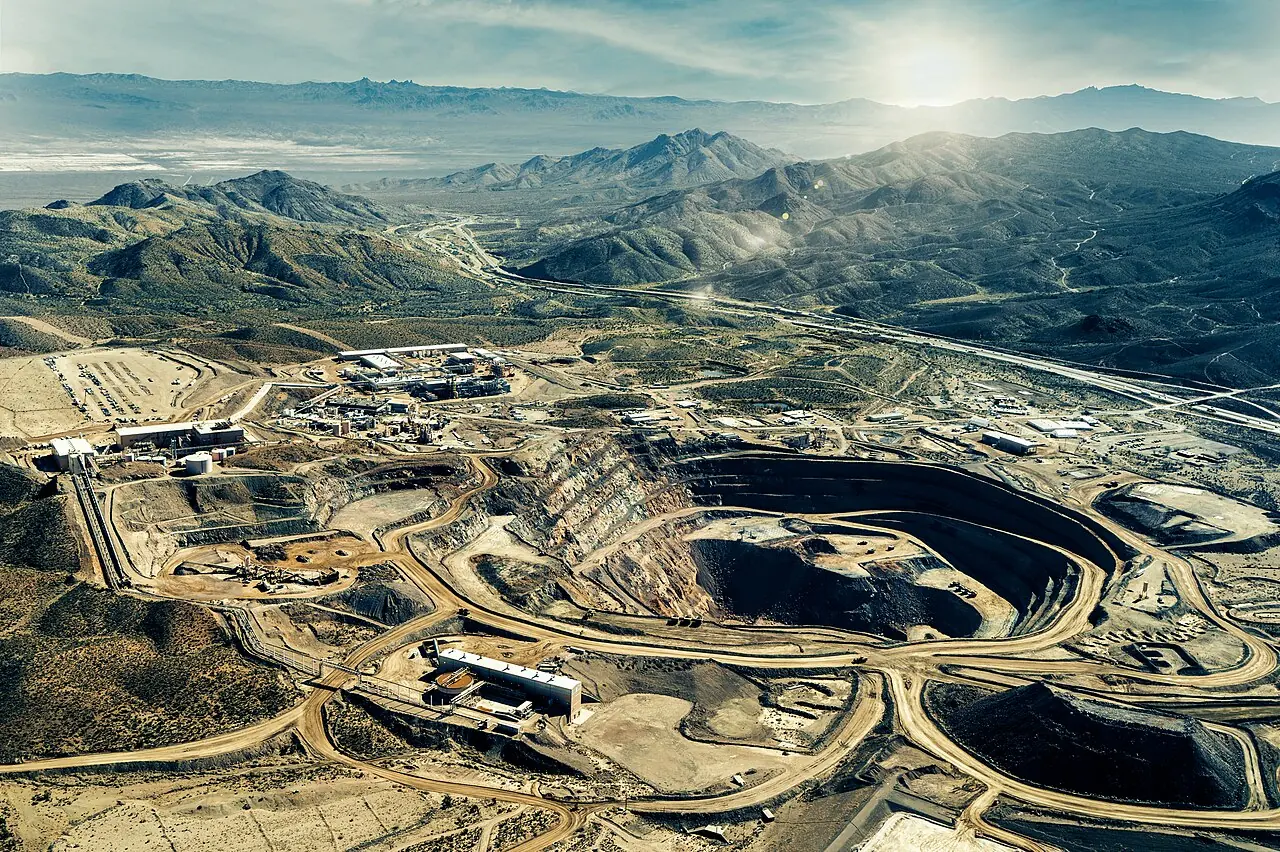
Germany is making a structured bet on Brazilian rare earths, and it brought the full toolkit: a €1 billion state-backed fund, a foreign minister, and a direct question about what it would take to finance a magnet plant on Brazilian soil.
On July 3, the German Embassy in Brasilia hosted a rare earth partnership event that gathered Johann Wadephul, Germany’s Federal Minister for Foreign Affairs, alongside representatives from Brazil’s Ministry of Mines and Energy (MME), Ministry of Finance, BNDES, and ApexBrasil. Six Brazilian project companies presented to the German delegation: Aclara, Brazilian Rare Earths, Cabo Verde Mineração, Rare Earth Americas, St George Mining, and Viridis Mining and Minerals.
What’s happening
The event was not a generic trade mission. It was a targeted attempt to match German capital and technology with Brazilian rare earth projects at varying stages of development, from exploration through licensing to metallurgical testing.
The German message, as reported by CNN Brasil, was explicit: Berlin wants to be a partner, not merely a buyer. That means equity participation, technology transfer, and offtake structures that tie Brazilian production into German and EU industrial supply chains.
A concrete signal came during the event when German embassy trade and economy representatives raised the possibility of supporting MagBras, Brazil’s national rare earth magnet production initiative, and asked what kind of backing would be needed to move it forward.
MagBras is the most advanced downstream rare earth project in Latin America. Based at the CIT Senai ITR facility in Lagoa Santa, Minas Gerais, it aims to build a complete domestic chain from ionic clay feedstock to NdFeB permanent magnets. The project received R$73.3 million from Brazil’s Mover program and has already processed its first 20 kg batch of rare earth carbonate from Meteoric Resources’ Caldeira project. If Germany’s Raw Materials Fund were to enter, it would mark the first foreign institutional capital directly into Brazil’s magnet manufacturing layer.
Brazil angle
Brazil holds the world’s third-largest rare earth reserves, but only one mine is in commercial production: Serra Verde in Goiás, which USA Rare Earth acquired in April 2026 for approximately $2.8 billion. The rest of the pipeline is pre-revenue, pre-construction, and hungry for capital.
The six companies at the embassy event illustrate the breadth of that pipeline:
- Viridis Mining (Colossus project, Minas Gerais): 215 Mt resource, demonstration plant producing mixed rare earth carbonate, targeting final investment decision in H2 2026 and production by end-2028. BNDES financing already secured.
- Aclara Resources (Carina module, Goiás): Heavy rare earth focus (dysprosium, terbium), feasibility stage, with a planned US separation plant in Louisiana. DFC support for the feasibility study.
- Brazilian Rare Earths (multiple ionic clay deposits): Definitive feasibility study expected Q2 2026.
- St George Mining (Araxá, Minas Gerais): 40.6 Mt carbonatite resource, hard-rock deposit with niobium co-product, targeting 2029.
- Rare Earth Americas (Alpha and Constellation projects, Bahia and Minas Gerais): Combined >1 billion tonnes of ionic clay mineralization, NYSE American IPO filing in progress.
- Cabo Verde Mineração: Ionic clay project with TREO grades above 3,000 ppm, early stage.
For Brazil, the strategic question is whether it can avoid the traditional commodity trap: exporting unprocessed ore while importing finished magnets. The Lula administration has made local value-add a priority, and the presence of MME, BNDES, and ApexBrasil at the embassy event signals government-level coordination to ensure that any German investment includes downstream commitments.
Laudemir Müller, president of ApexBrasil, reinforced this framing on the record: “I won’t call it a preference, but we have more proximity [with the EU]. With some companies, some mindsets, some attitudes. I think Germany has that leadership and ability to coordinate with various funds and companies.”
US angle
The United States has been the most visible Western actor in Brazilian critical minerals. The DFC financed Aclara’s feasibility study. USA Rare Earth’s $2.8 billion Serra Verde acquisition was the largest rare earth transaction in the Western Hemisphere. Washington’s interest is real and capitalized.
But Brazilian interlocutors, as reported by CNN Brasil, view the European approach as carrying less political noise and more openness to technology transfer and local industrialization. The German Raw Materials Fund, operated by KfW, is structured as a minority equity investor (typically ~25%) alongside industrial partners, with ticket sizes of €50 million to €150 million per project. It requires binding offtake agreements to German or EU facilities, but it does not require Brazilian projects to cede control or relocate processing.
That structure matters. US engagement has sometimes come with strings attached: DFC financing can carry policy conditions, and US strategic stockpiling programs like the Defense National Stockpile Center prioritize defense-sector offtake. Germany’s fund, by contrast, is industrial-demand driven: automotive, wind, electronics, defense. It is a demand pull, not a security push.
For US investors and policymakers, the read is that Europe is now competing directly for Brazilian rare earth partnership, and Berlin is offering a model that may be more palatable to Brasilia’s industrialization goals.
China angle
China dominates roughly 70% of rare earth mining and 90% of separation and magnet production. That concentration is the entire reason Western governments are in Brazil at all.
Germany’s embassy event comes after Wadephul’s own rare earth diplomacy in Beijing in June 2025, where he warned that Chinese trade restrictions on rare earths posed a central threat to German industry. China responded by saying it would handle European license applications “constructively.” The constructiveness has limits. Beijing’s export controls on gallium, germanium, graphite, tungsten, and antimony in 2024-2025 showed that China treats critical minerals as leverage.
The EU’s response is structural diversification. Commissioner Jozef Síkela visited Brazil in June 2026, toured Viridis’s demonstration plant, and selected four Brazilian projects (including Viridis’s rare earth operation) for accelerated EU-Brazil supply chain collaboration. The July 3 embassy event is the follow-through: moving from commissioner-level intent to fund-manager-level deal flow.
For China, the risk is not that Brazil replaces its supply overnight. The risk is that Brazil becomes the anchor of a Western rare earth pipeline that includes separation in Brazil, magnet production in Brazil or Europe, and end-use in German EVs and wind turbines. That pipeline does not exist today. Events like this one are how it gets built.
What it means
The Tantalum AI Materials Index (TAI-M) tracks rare earth exposure through the REMX ETF and semiconductor demand through SOXX. Neither directly captures Brazilian project-level risk. But the index framework treats rare earths as an AI infrastructure input because NdPr magnets power the cooling fans, motors, and actuators inside data centers and the EVs that electrify the grids feeding them.
If Germany funds Brazilian rare earth separation and magnet production, the supply chain resilience of those inputs improves. That is a long-dated, capital-intensive outcome. The near-term signal is geopolitical: the EU is now a committed, capitalized competitor to the US and China for Brazilian mineral partnership.
What to watch
- MagBras financing: Will the German Raw Materials Fund make a formal commitment? The fund’s first investment was €150 million into Vulcan Energy’s Lionheart lithium project in December 2024. A MagBras ticket would be the fund’s first rare earth and first Brazil play.
- Viridis FID: The company expects final investment decision in H2 2026. German offtake or equity could accelerate that timeline.
- EU-Mercosur ratification: Wadephul’s visit included EU-Mercosur advocacy. If the trade agreement moves, rules-of-origin and investment protections for critical minerals projects could sharpen.
- Serra Verde integration: USA Rare Earth’s acquisition closed in April 2026. How quickly it scales, and whether it partners with German or EU offtakers, will set the competitive template.
- China response: Beijing has tools, price pressure, and market power. Watch for Chinese investment or offtake moves into Brazilian projects as a counterweight.


